Where Does Your Remittance Go? The 3-Part OFW Money System
By Lolo Melvyn | Published in OFW Real Talk
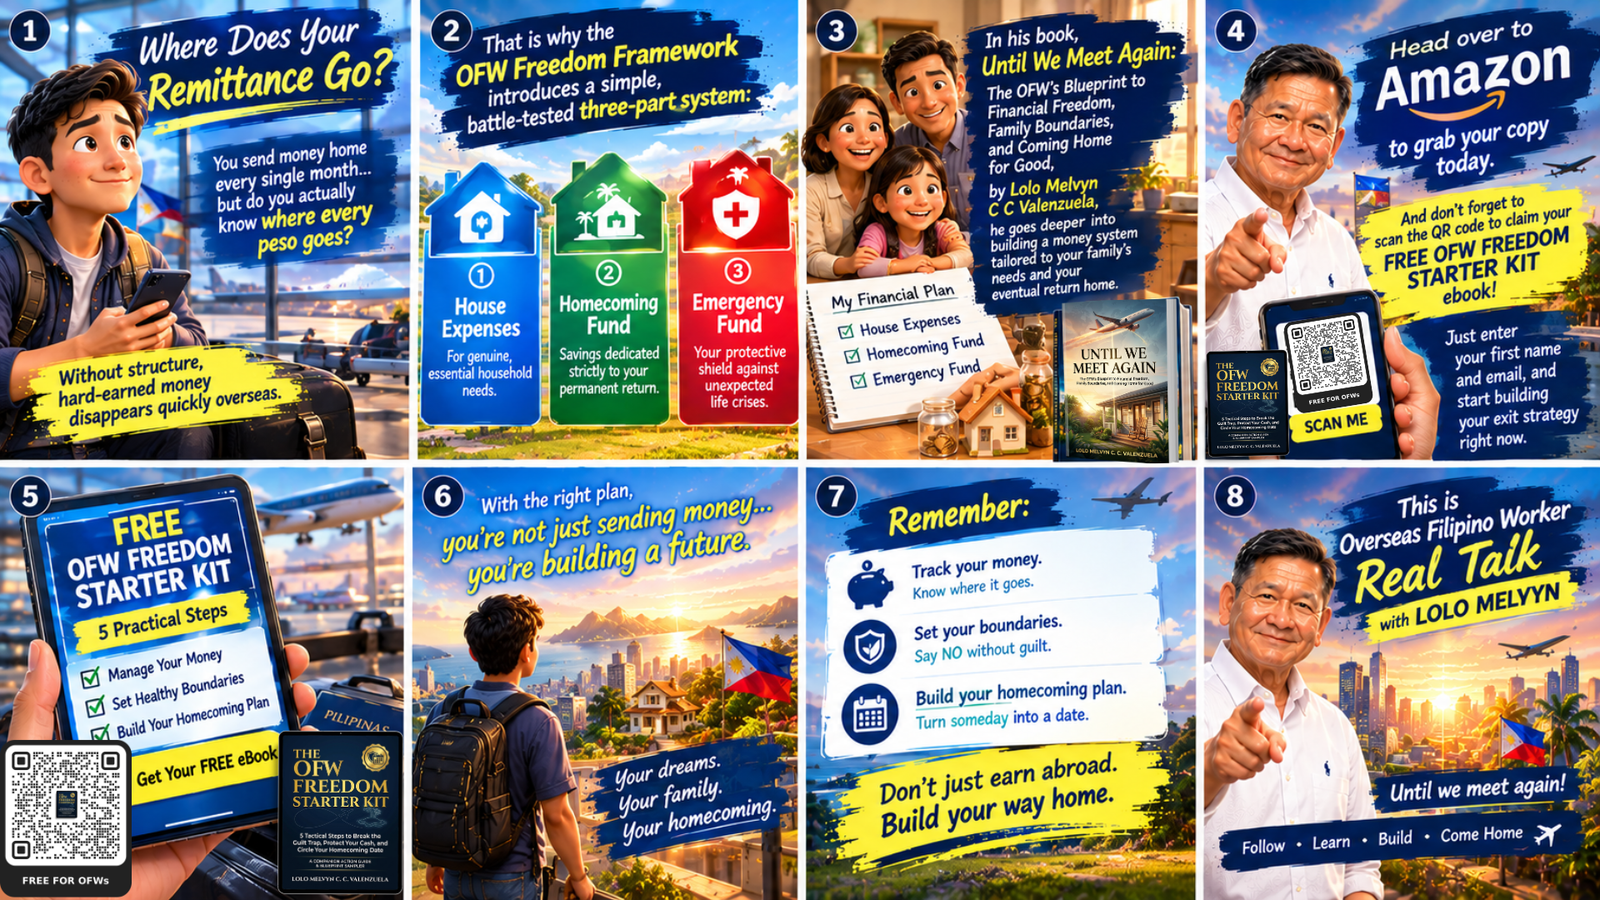
Where Does Your Remittance Go? Learn how to structure your monthly money transfers into House Expenses, Homecoming Fund, and Emergency Shield.
📌 Official Freedom Resources & Quick Links:
- 📖 Get the Book on Amazon: Until We Meet Again on Amazon
- 🎁 Download FREE Ebook: Claim The OFW Freedom Starter Kit
- 🌐 Explore Official Guides: Official Website | Lolo Melvyn Bookshop | How To Say No Without Guilt | You Are Not An ATM Guide | Starter Kit Explainer | Someday Is Not A Plan | Working Abroad Without a Finish Line
Let me ask you a serious question: Where Does Your Remittance Go every single month? You send money home faithfully, month after month, year after year… but do you actually know where every single peso goes? Or does it seem to vanish into thin air the moment it reaches the Philippines?
Without structure, hard-earned money disappears quickly overseas. Overseas Filipino Workers work long hours, face extreme sacrifices, and endure distance, only to discover that their hard work produces very little personal savings back home.
That is why the Overseas Filipino Worker Freedom Framework introduces a simple, battle-tested three-part system designed to give you total control over your salary:
- First: House Expenses—allocated strictly for genuine, essential household needs.
- Second: Homecoming Fund—savings dedicated strictly to your permanent return.
- Third: Emergency Fund—your protective shield against unexpected life crises.
In the book, Until We Meet Again: The OFW’s Blueprint to Financial Freedom, Family Boundaries, and Coming Home for Good, author Lolo Melvyn goes deeper into building a money system tailored to your family’s needs and your eventual return home. Read on to learn how answering Where Does Your Remittance Go will transform your financial security.
📺 Watch Lolo Melvyn’s Real Talk Video:
Table of Contents
- The Unseen Danger: Why Unstructured Remittances Disappear
- The 3-Part Framework: Where Does Your Remittance Go?
- Part 1: Budgeting Genuine House Expenses
- Part 2: Securing Your Homecoming Fund (Your Exit Strategy)
- Part 3: Building the Emergency Fund Shield
- Executing Your Return with the OFW Freedom Starter Kit
- Conclusion: Stop Guessing Where Does Your Remittance Go
The Unseen Danger: Why Unstructured Remittances Disappear
Every single month, millions of workers send billions of pesos back to the Philippines, as documented by national institutions such as the Department of Migrant Workers (DMW) and the Overseas Workers Welfare Administration (OWWA). Yet, despite earning foreign salaries, many OFWs return home with empty savings accounts. Why?
The core issue stems from sending lump-sum payments without defining Where Does Your Remittance Go. When money arrives in a single account without labels, family members treat it as disposable cash. Essential utilities get mixed up with non-essential spending, dining out, and loans to extended relatives.
If you fail to clarify Where Does Your Remittance Go, you fall into the trap of Working Abroad Without a Finish Line. To protect your hard work, you must transition from sending casual hand-outs to running a structured remittance system.
The 3-Part Framework: Where Does Your Remittance Go?
In Until We Meet Again Lolo Melvyn, Lolo Melvyn provides a clear answer to the question: Where Does Your Remittance Go? He divides every remittance transfer into three distinct, non-negotiable accounts.
The 3-Part Remittance System
1. HOUSE EXPENSES: Basic Needs (Food, Utilities, Education)
2. HOMECOMING FUND: Locked Return Savings (Transition Capital)
3. EMERGENCY FUND: Crisis Shield (Medical & Unexpected Events)
By using this exact structure, you will never have to wonder Where Does Your Remittance Go again. Each peso has an assigned task before it leaves your hands.
Part 1: Budgeting Genuine House Expenses
The first destination when asking Where Does Your Remittance Go is House Expenses. This allocation covers survival needs for your immediate family in the Philippines:
- Nutritional Support: Monthly groceries and daily food allowances.
- Utilities & Housing: Electricity, water, internet, and basic rent or maintenance.
- Education Costs: School tuition, uniforms, and essential educational materials.
To keep money focused on basic needs, pay utility bills directly using digital service providers like Bayad Center. Distributing funds through dedicated channels helps ensure that your household budget stays intact.
When relatives ask for funds outside this budget, learn How To Say No Without Guilt and remind them that your household money is reserved strictly for essential survival needs.
Part 2: Securing Your Homecoming Fund (Your Exit Strategy)
The second part of the answer to Where Does Your Remittance Go is your Homecoming Fund. This account belongs exclusively to you and is created to fund your permanent return to the Philippines.
Unlike monthly living expenses, your Homecoming Fund must never be accessed for daily household spending. It serves as your financial bridge when you transition out of working abroad.
Growing Your Homecoming Fund via Regulated Philippine Institutions:
Keep your return savings growing safely in regulated financial programs in the Philippines, such as:
- Pag-IBIG MP2 Savings: High-yield, government-guaranteed tax-free dividend growth managed via the Pag-IBIG Fund Official Portal.
- SSS Retirement Pensions: Voluntary social protection managed through the Social Security System (SSS) Portal.
- Regulated Banking Institutions: High-yield savings supervised by the Bangko Sentral ng Pilipinas (BSP) and insured up to legal limits by the Philippine Deposit Insurance Corporation (PDIC).
For additional strategies on establishing financial boundaries, read our dedicated guide explaining why You Are Not An ATM.
Part 3: Building the Emergency Fund Shield
The final destination when asking Where Does Your Remittance Go is your Emergency Fund Shield. Without a dedicated emergency fund, unexpected events can quickly destroy your savings.
An emergency fund covers sudden medical bills, unexpected repairs, or job transitions without forcing you to borrow money. Keep this buffer separate from both your daily household budget and your homecoming savings.
Maintaining a dedicated emergency fund gives you peace of mind while working abroad. For a complete step-by-step framework, review our guide on why Someday Is Not A Plan.
Executing Your Return with the OFW Freedom Starter Kit
Knowing Where Does Your Remittance Go allows you to calculate your target return date with confidence. Tracking your expenses helps you determine your **Freedom Number**—the exact monthly income required to support your family back in the Philippines.
The Freedom Target Formula
[ Realistic Monthly Family Expense ] x 12 Months = Your Annual Freedom Target
To help you map out every stage of your return, download our complimentary guide: The OFW Freedom Starter Kit. You can also read our OFW Freedom Starter Kit Explainer Page to set up your personal return timeline.
Conclusion: Stop Guessing Where Does Your Remittance Go
Stop letting your hard-earned foreign earnings disappear without a trace. Take control of your salary by answering Where Does Your Remittance Go, setting clear allocations, and building a structured plan to return home permanently.
Take charge of your financial journey today with these official resources from Lolo Melvyn C. C. Valenzuela:
Pingback: What Is Your Freedom Number? OFW Exit Strategy
Pingback: Don’t Sacrifice Your Children’s Future: OFW Guide
Pingback: Don’t Fly Home Unprepared: OFW Landing Strategy